
SP Angel – Morning View – Thursday 13 09 18
Trade negotiation offer give metals strong boost
MiFID II exempt information – see disclaimer below
Anglo Asian Mining Plc* (AAZ LN) – First comprehensive review of mineralisation at Gedabek via airborne geophysical survey
Bushveld Minerals* (BMN LN) - Acquisition of SOJUTZ stake looks good for Bushveld (Bushveld Minerals now holds 75% of Vametco)
Strategic Minerals* (SML LN) – Update on the sale of gold tenements
Lithium shortage could slow Tesla production
- Tesla Inc’s race to secure battery material could be hampered by delays at Mt. Holland mining project which are set to supply the electric-vehicle maker. A court in Perth recommended Western Australia’s mining ministry not to approve an exemption from past minimum exploration expenditure obligations at the Mt. Holland spodumene project, with development at the project slowed if the ministry doesn’t award the exemption, according to co-owner SQM.
- In May, Tesla signed a three-year lithium hydroxide supply contract with co-owner Kidman Resources Ltd. Tesla’s decision to strike a deal with a junior miner that that isn’t expected to start producing until 2021 shows how electric-car and battery makers are rushing to get supply of the mineral.
- Bloomberg NEF analyst notes “this is going to be a concern to Tesla – they had hopes to lock in supply by signing this off-take with Kidman. It could certainly impact Tesla significantly if Tesla doesn’t have other supply deals in place”.
- Following years of under-supply, the market will be in a small surplus until 2020 as SQM increases production capacity in Chile and two new mines are built in Australia, according to a BNEF report. Still, any delays could tip the balance -- and new lithium projects tend to encounter administrative hurdles or suffer longer-than-expected ramp ups, according to the report.
- “There are other delays that could still hit the project during ramp up, such as delays related to owners not having operated these types of mine before,” BNEF analyst said. “If delays go on for a number of years and the mine is not online by 2024 or 2025, we would start to see potential under-supply in the lithium market.”
Autonomous Mercedes concept shape-shifts from cargo van to rideshare vehicle
- The Mercedes-Benz Vision Urbanetic concept can switch bodies, going from cargo van to ridesharing shuttle – it consists of a flat chassis and multiple bodies that can be interchanged
- A passenger version can accommodate up to 12 people and can be substituted for a cargo box, with all mechanical components housed in the chassis
- The bodies are designed to be switched manually or via and automatic system that takes only a few minutes
Solid-state battery start-up secures backing from several automakers
- Solid Power claims to have achieved a breakthrough by incorporating a high-capacity lithium metal anode in lithium batteries, creating a solid-state cell with an energy capacity 2-3x higher than conventional lithium-ion
- Investment so far has come for company such as A123 Systems and BMW
- This week they have announced the addition of Hyundai and Samsung to the list as they close a $20m series of A round financing
Sodium-ion battery replacement
- Researchers are entertaining the possibility of turning to sodium for the next wave of rechargeable batteries for electronic devices and electrical vehicles
- Researchers from the University of Birmingham may have found a way to replace the lithium in lithium-ion batteries with a cheaper sodium option that will compete with lithium for capacity, speed of charge, energy and power density.
|
Dow Jones Industrials |
+0.11% |
at |
25,999 | |
|
Nikkei 225 |
+0.96% |
at |
22,821 | |
|
HK Hang Seng |
+2.01% |
at |
26,875 | |
|
Shanghai Composite |
+1.15% |
at |
2,687 | |
|
FTSE 350 Mining |
+0.73% |
at |
16,012 | |
|
AIM Basic Resources |
+0.64% |
at |
2,160 |
Economics
Brent may break the $70-80/bbl range should global producers fail to offset falling oil output from Venezuela and announced sanctions against production from Iran, the IEA said.
- Exports from Iran have fallen by nearly 500,000bbl per day since May as counteragents cut their purchases on concerns over sanctions from the US.
- However, it is unclear what production response may be from other producers with OPEC countries estimated to have 2.7mbbl of spare production capacity available with 60% of that located in Saudi Arabia.
- Currently, global supply is reported to be running at record levels of 100mbbl with OPEC countries production at nine months high.
US – US Equity futures and European stocks were steady while Asian shares ended the longest losing streak in 16 years as US Treasury Secretary reached out to Beijing to offer another round of trade talks.
- China said on Thursday it welcomed an invitation by the US to hold a new round of negotiations.
- The MSCI Asia Pacific Index gained for the first time in 11 sessions, with equities climbing in Shanghai.
- Producer prices changes released yesterday point to continued inflation pressures supporting the case for tighter monetary policy stance.
- Excluding volatile trade, food and energy components, PPI measure climbed 0.1%mom or 2.9%yoy in August from 0.3%mom/2.8%yoy the previous month.
UK – The BoE is due to announce no change in benchmark rates today.
- The pound is flat against the US$ this morning trading above the 1.30 mark after having appreciated recently on improved prospects of averting a no-deal Brexit.
- On the property market, weak performance in London and in the south east dragged down UK house prices in August, the latest data from the Royal Institute of Chartered Surveyors showed.
- Respondents highlighted that sales were stabilising in London following a sharp drop at the end of last year but sales in the south east were still declining.
Turkey – President Erdogan has appointed himself chairman of the nation’s sovereign wealth fund with $200bn AUM.
- Berat Albayarak, Erdogan’s son-in-law, would act as his deputy.
- On a separate note, the central bank is set to hold make an announcement on the monetary policy today with market expectations for an increase in rates to 21.0%, up from 17.75%.
- The central bank has been criticised lately for the reluctance to put rates up despite an accelerating rate of inflation which soared to 18%.
- The lira is slightly weaker against the US$ as opposed to other EM currencies.
Currencies
US$1.1619/eur vs 1.1583/eur yesterday Yen 111.50/$ vs 111.51/$ SAr 14.917/$ vs 15.145/$ $1.304/gbp vs $1.301/gbp 0.718/aud vs 0.711/aud CNY 6.849/$ vs 6.872/$
Commodity News
Precious metals:
Gold US$1,204/oz vs US$1,194/oz yesterday
- Gold prices surge above the $1,200 threshold as the US proposes another round of talks with Beijing to avoid escalation of trade war rhetoric, harming the dollar. Senior officials led by Treasury Secretary Steven Mnuchin have proposed another round of trade talks with China to avoid rising risks with Donald Trump’s trade war.
- Larry Kudlow, director of Trump’s National Economic Council notes “it’s a positive thing. We are in communication right now and you could say that communication has picked up a notch”. US equities also rose on the expectations the development could ease growing tensions. The Dow Jones Industrial Average turned positive and emerging market assets rallied on the news.
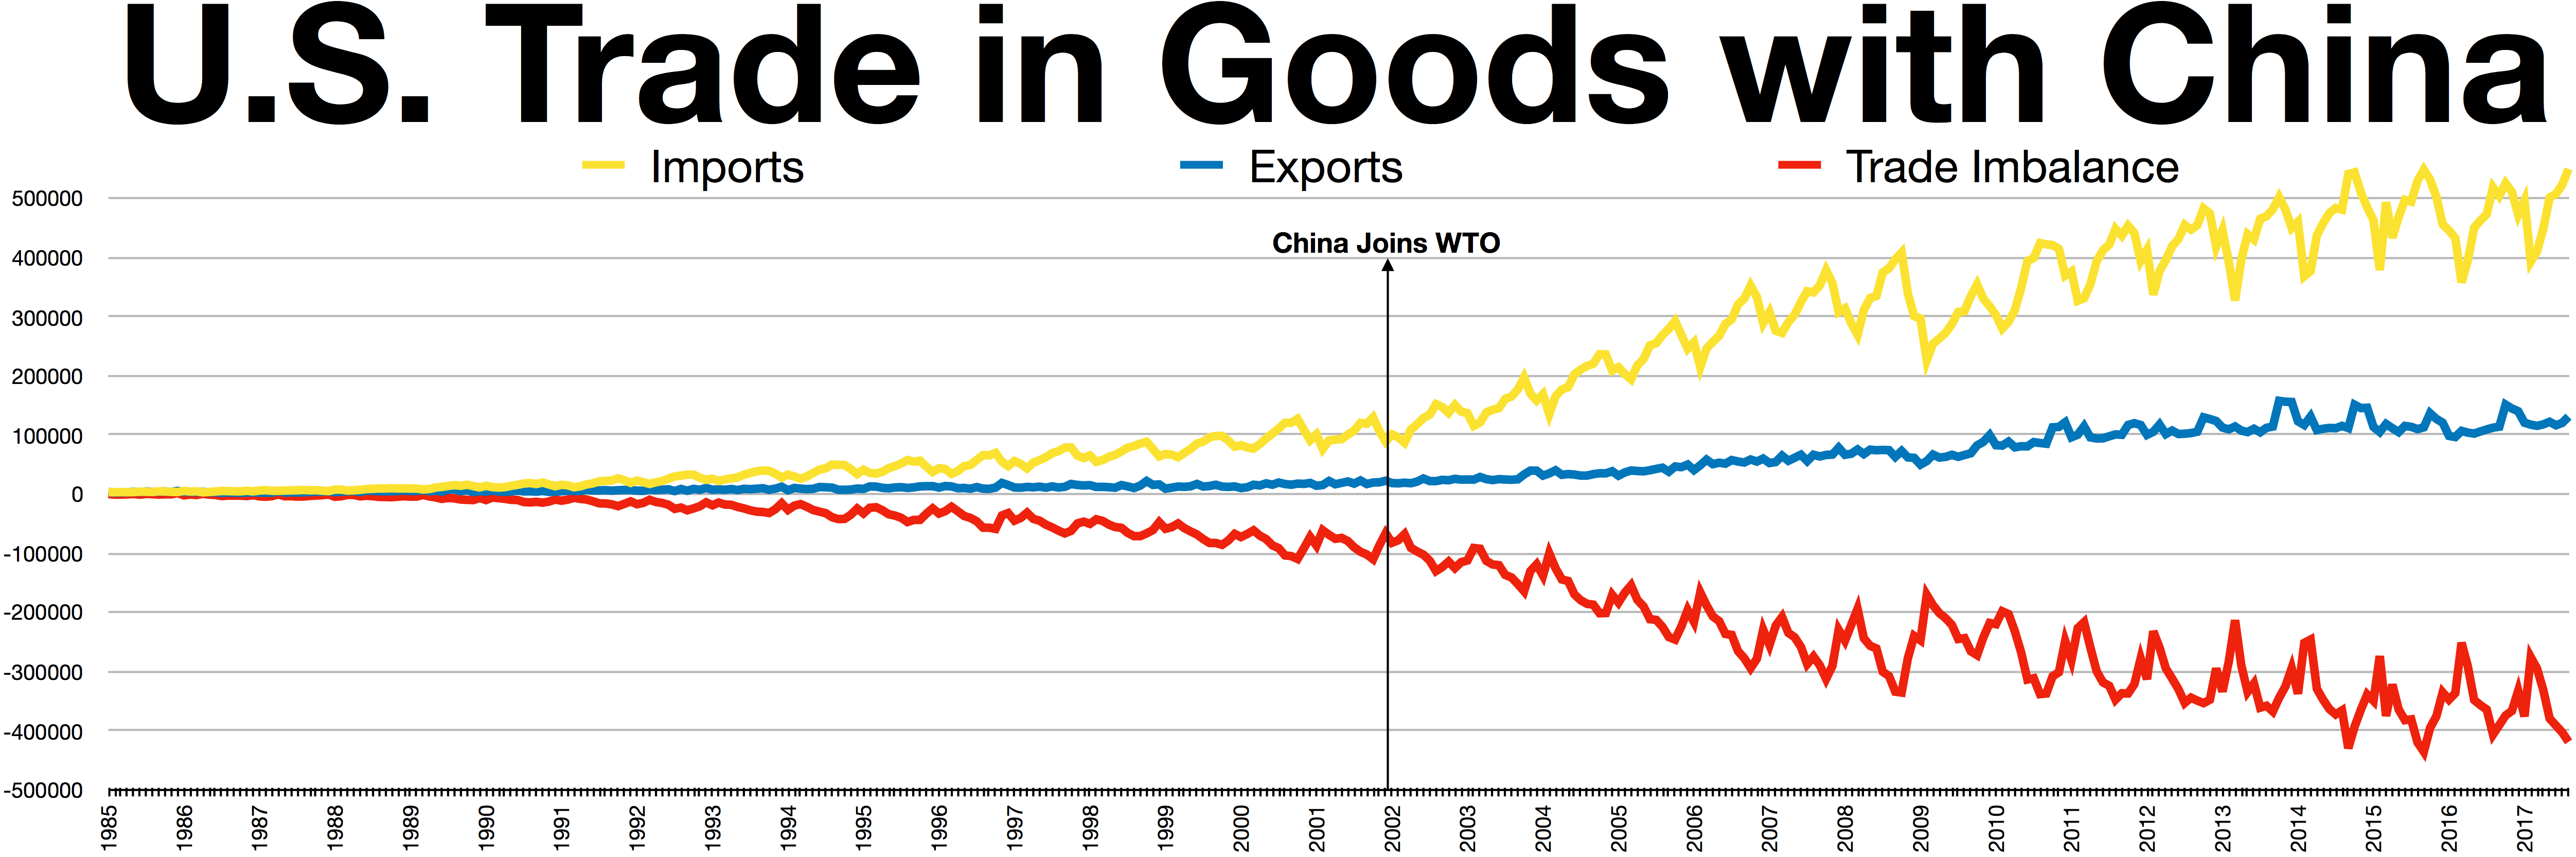
- The White House has sought to pressure Beijing to reduce its trade surplus with America and protect intellectual property rights of U.S. companies. The Trump administration has already imposed duties on $50bn of Chinese exports since July, which spurred immediate in-kind retaliation from Beijing.
- Trump hasn’t yet pulled the trigger on tariffs on an additional $200bn in Chinese goods. A comment period for that round of tariffs expired last week without U.S. action. He said last week that he’s lined up an additional $267bn of Chinese products for duties “on short notice if I want to,” which would cover virtually everything the country exports to the US, including consumer goods such as clothing and Apple smartphones.
- Concerns surrounding the harmful impact on global economic growth have been growing as China said it would be forced to retaliate against all of the US measures.
- Kudlow has suggested that Trump would be willing to meet with President Xi Jinping to bridge to gap in demands, possibly at a G-20 meeting in Argentina in late November.
Gold ETFs 67.7moz vs US$67.7moz yesterday
Platinum US$803/oz vs US$790/oz yesterday
- While deflated prices have drawn down platinum miners, rallying co-produced palladium and rhodium has more than supported average sales. No.2 producer, Impala Platinum Holdings Ltd. still managed to increase its average price per ounce as palladium prices jumped 35% and rhodium surged 90% according to the company full-year earnings statement.
- Elevated prices helped Implats, as the company is known, offset the effects of cheaper platinum and a stronger local currency, for a 5% increase in its so-called rand basket price for metals. Better than expected company results, including costs, caused Implats to jump as much as 7.2%.
- The divergence within the platinum-group-metal family is likely to continue, the Johannesburg-based miner said. While deposits in top supplier South Africa mostly contain platinum, other metals such as palladium, rhodium and nickel are also present and are helping to boost revenue as demand falters for the silvery metal.
- Platinum prices have halved since a 2011 peak as demand for the metal used to curb pollution from diesel vehicles weakens, partly due to slower sales of the cars in Europe. Palladium has held up better as the metal is primarily used in catalytic converters for gasoline cars.
- “The immediate fundamentals for both palladium and rhodium remain strong, largely due to expected growth in the global internal combustion engine automotive market and tighter emissions regulations,” Implats said. Platinum, on the other hand, is likely to see soft demand for at least another three years, it said.
Palladium US$978/oz vs US$975/oz yesterday
Silver US$14.21/oz vs US$14.14/oz yesterday
Base metals:
Copper US$ 6,026/t vs US$5,907/t yesterday
- Base metals broadly gain, with copper breaking the $6,000/t level, on optimism on prospects for US-China trade talks. LME copper climbed +2% to $6,026, while rising +1.8% in Shanghai.
- News drove +2% rise in LMEX index of six base metals on Wednesday, the most in almost 4 weeks.
Aluminium US$ 2,050/t vs US$2,061/t yesterday
Nickel US$ 12,650/t vs US$12,325/t yesterday
Zinc US$ 2,385/t vs US$2,351/t yesterday
Lead US$ 2,047/t vs US$1,997/t yesterday
Tin US$ 19,050/t vs US$18,955/t yesterday
Energy:
Oil US$79.3/bbl vs US$79.3/bbl yesterday
Natural Gas US$2.832/mmbtu vs US$2.837/mmbtu yesterday
Uranium US$27.00/lb vs US$27.00/lb yesterday
Bulk:
Iron ore 62% Fe spot (cfr Tianjin) US$67.5/t vs US$67.4/t
Chinese steel rebar 25mm US$692.1/t vs US$689.7/t
Thermal coal (1st year forward cif ARA) US$96.3/t vs US$96.6/t
Premium hard coking coal Aus fob US$182.2/t vs US$182.2/t
Other:
Cobalt LME 3m US$63,000/t vs US$62,000/t
Tungsten APT European US$275-290/mtu vs US$275-290/mtu
Company News
Anglo Asian Mining Plc* (AAZ LN) 43p, Mkt Cap £49.0m – First comprehensive review of mineralisation at Gedabek via airborne geophysical survey
Buy – 77p
- Anglo Asian Mining plans to undertake an airborne geophysical survey over the entire Gedabek contract area in Azerbaijan to identify additional gold and copper mineralised occurrences and generate future drill targets. The company contracts Geotech Limited, one of Canada’s leading airborne geophysical companies, to conduct the survey.
- The survey represents the first airborne geophysical data to be collected over the entire 300km² Gedabek area. A total of 4,512 linear km’s are planned to be flown.
- The heli-borne electromagnetic survey will employ an innovative Z-Axis Tipper Electromagnetic system (ZTEM) which uses the natural magnetic field of the Earth. The system has been excellently applied to mapping surface geology, while deep penetration is suitable for porphyry copper-gold and epithermal copper-gold-silver exploration.
- Stephen Westhead, Anglo Asian Group Director of Geology and Mining notes “we are already aware of many gold and copper mineral occurrences at Gedabek”, with the survey providing data about geophysical anomalies arising from mineral trends and occurrences.
- The geophysical “signatures” of known deposits such as Ugur will assist identifying targets, allowing for focused future ground-based geophysical investigative techniques including geological mapping, geochemical surveys and drilling.
Conclusion: The airborne survey provides an efficient first geophysical dataset for the large Gedabek contract area, and will assist in identifying prospective exploration targets for focused and higher resolution ground-based follow up work.
*SP Angel act as Nomad and broker to Anglo Asian Mining
Bushveld Minerals* (BMN LN) 22.3p, mkt cap £247.0m - Acquisition of SOJITZ stake looks good for Bushveld (Bushveld Minerals now holds 75% of Vametco)
- Bushveld Minerals continue to add value to their business through canny negotiation.
- The unofficial, ‘unprotected’ strike at Vametco has come at an opportune time for Bushveld during the SOJITZ negotiations.
- The agreed $20m deal with SOJITZ looks good from a cash perspective with $17.5m for the stake and $2.5m for unpaid dividends.
- This gives Bushveld 75% of the Vametco operation which should be both earnings and value enhancing in our view.
- Unofficial stoppages, demonstrations and maintenance served to reduce first half production and to dramatically cut the production for the remainder of the year as the Bushveld team work to resolve issues left by the previous management.
- Bushveld have offered a R20,000 payment for each worker who would have been in the previously offered share incentive scheme. That’s just over $1,300 per employee and is a significant and no-doubt welcome bonus.
- The good bit is that vanadium prices continue to rise beyond expectation and the South African rand continues to fall, as have many other ‘developing’ market economies.
- The combination of the stronger vanadium price and weaker rand serves to offset much of the loss of earnings from the plant stoppage.
- The increase in Bushveld’s stake to 75% from 59.1% will further enhance earnings from their share of the business if vanadium prices remain strong and production restarts relatively soon.
- While politics are never far from the coal face in South Africa we respect that Vametco employees have worked hard to expand the business this year. We hope the workforce will come back to work soon and that production will return to its expanded level relatively quickly.
- We will publish updated forecasts to take account of the 75% stake shortly.
Conclusion: The SOJITZ deal looks good for Bushveld from an earnings perspective and further consolidates their ownership of Vametco. We look forward to further news on the return to work soon.
*SP Angel act as Nomad and broker to Bushveld Minerals
Strategic Minerals* (SML LN) 1.6p, Mkt Cap £21.8m – Update on the sale of gold tenements
- Strategic Minerals has confirmed that it has now exchanged contracts on the previously announced sale of four exploration tenements considered prospective for gold, currently held by its wholly owned Central Australian Rare Earths (CARE), to ASX listed Great Southern Mining.
- The company has received a non-refundable deposit of A$50,000 and expects the balance of the consideration, comprising a further A$50,000 and 1m shares in Great Southern Mining shares at an issue price of A$0.045/share, within one month.
- Managing Director, John Peters, explained that the “Additional funding arising from this sale is likely to be applied to further drilling around Hanns Camp, notably at Hanns Camp South, which remains highly prospective for nickel sulphide mineralisation.”
Conclusion: The sale of the gold tenements is proceeding on track and should allow Strategic Minerals’ team at CARE to focus on its primary objective of nickel/cobalt and rare-earths exploration.
*SP Angel act as Nomad and broker to Strategic Minerals
Analysts
John Meyer – 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
Phil Smith (Technology) – 0203 470 0475
Zac Phillips (Oil & Gas) – 0203 470 0481
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
DISCLAIMER
This note has been issued by SP Angel Corporate Finance LLP (“SP Angel”) in order to promote its investment services.
This information is a marketing communication for the purpose of the European Markets in Financial Instruments Directive (MiFID) and FCA’s Rules. It has not been prepared in accordance with the legal requirements designed to promote the independence or objectivity of investment research.
This document is not based upon detailed analysis by SP Angel of any market; issuer or security named herein and does not constitute a formal research recommendation, either expressly or otherwise.
The value of investments contained herein may go up or down. Where investment is made in currencies other than the base currency of the investment, movements in exchange rates will have an effect on the value, either favourable or unfavourable. Securities issued in emerging markets are typically subject to greater volatility and risk of loss.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. This information is for the sole use of Eligible Counterparties and Professional Customers only and is not intended for Retail Clients, as defined by the rules of the Financial Conduct Authority (“FCA”) and subject to SP Angel’s Terms of Business as published or communicated to clients from time to time.
It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. This document should not to be relied upon as authoritative or taken in substitution for the exercise of you own commercial judgment. SP Angel is not responsible for any errors, omissions or for the results obtained from the use of the information in this document.
This document has been prepared on the basis of economic data, trading patterns, actual market news and events, and is only valid on the date of publication. SP Angel does not make any guarantee, representation or warranty, (either expressly or implied), as to the factual accuracy, completeness, or sufficiency of information contained herein. This document has been prepared by the author based upon information sources believed to be reliable and prepared in good faith.
SP Angel, its partners, officers and or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SP Angel Corporate Finance LLP is a company registered in England and Wales with company number OC317049 and whose registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SP Angel Corporate Finance LLP is authorised and regulated by the Financial Conduct Authority whose address is 25, The North Colonnade, Canary Wharf, London E14 5HS and is a Member of the London Stock Exchange plc.