
MiFID II exempt information – see disclaimer below
SP Angel – Graphite Market Report
Graphite market driven by Li-ion battery growth and China environmental legislation
Key themes
- Recovering prices are driven by strengths in the steel industry, tightening Chinese environmental legislation and budding Li-ion battery demand
- Traditional consumption is expected to plateau with electric economy growth as the main driver for future graphite pricing
- Expandable graphite demand accelerating to dominate future markets on stringent construction trends, drawing significant large-flake deposit pressure
- Graphene R&D investment will drive an innovative technology sector
- China to become net importer of natural graphite due to the war on smog and diminishing domestic ore quality
- Future supply focus in Africa and Canada, targeting highest purity raw material. Significant upside is available for value-add products, with prospective miners transitioning into technology materials companies to maximising potential market capitalisation.
Price Outlook
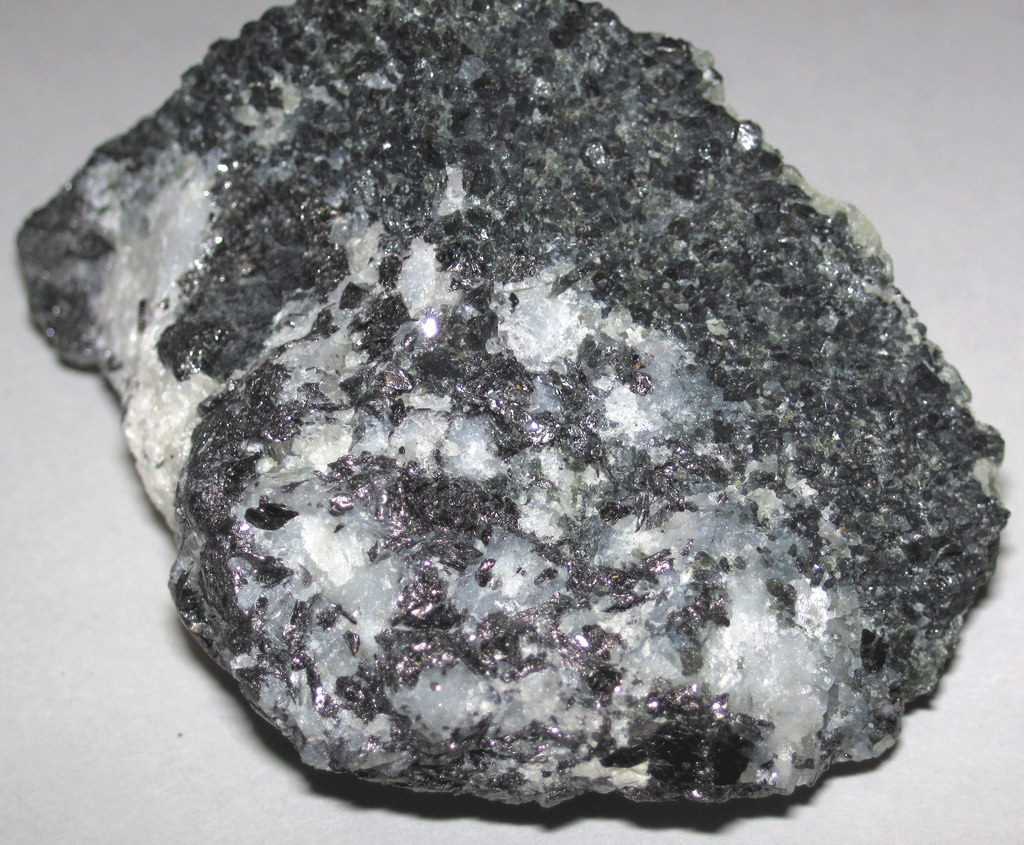
- Graphite is an allotrope (a chemically similar, structural modification of carbon), exhibiting both metallic and non-metallic properties which favour a vast number of end-use markets. Further to traditional steel manufacturing, the unique qualities of graphite, including very high thermal and electrical conductivity, lend itself to innovative battery and emerging technologies.
- Mined graphite is most commonly sold as a concentrate by private, direct negotiation, leading to opaque pricing structures. Pricing details are posted via minerals intelligence companies, for example ‘Industrial Minerals’, who provide guideline quoted prices with respect to long-term trends after surveying industry participants. Most natural graphite is typically sold to traders who upsell to intermediary refiners, polishers and shapers before retailed to final customers. With China dominating the market, responsible for 67% production in 2017 (source: USGS), the Asian powerhouse nation is setting the global standard for the commodity’s price.
See full report here for further details
Analysts
John Meyer – 0203 470 0490
James Mills - 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
Phil Smith (Technology) – 0203 470 0475
Zac Phillips (Oil & Gas) – 0203 470 0481
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
DISCLAIMER
This note has been issued by SP Angel Corporate Finance LLP (“SP Angel”) in order to promote its investment services.
This information is a marketing communication for the purpose of the European Markets in Financial Instruments Directive (MiFID) and FCA’s Rules. It has not been prepared in accordance with the legal requirements designed to promote the independence or objectivity of investment research.
This document is not based upon detailed analysis by SP Angel of any market; issuer or security named herein and does not constitute a formal research recommendation, either expressly or otherwise.
The value of investments contained herein may go up or down. Where investment is made in currencies other than the base currency of the investment, movements in exchange rates will have an effect on the value, either favourable or unfavourable. Securities issued in emerging markets are typically subject to greater volatility and risk of loss.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. This information is for the sole use of Eligible Counterparties and Professional Customers only and is not intended for Retail Clients, as defined by the rules of the Financial Conduct Authority (“FCA”) and subject to SP Angel’s Terms of Business as published or communicated to clients from time to time.
It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. This document should not to be relied upon as authoritative or taken in substitution for the exercise of you own commercial judgment. SP Angel is not responsible for any errors, omissions or for the results obtained from the use of the information in this document.
This document has been prepared on the basis of economic data, trading patterns, actual market news and events, and is only valid on the date of publication. SP Angel does not make any guarantee, representation or warranty, (either expressly or implied), as to the factual accuracy, completeness, or sufficiency of information contained herein. This document has been prepared by the author based upon information sources believed to be reliable and prepared in good faith.
SP Angel, its partners, officers and or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SP Angel Corporate Finance LLP is a company registered in England and Wales with company number OC317049 and whose registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SP Angel Corporate Finance LLP is authorised and regulated by the Financial Conduct Authority whose address is 25, The North Colonnade, Canary Wharf, London E14 5HS and is a Member of the London Stock Exchange plc.