

21 February 2019
News
Few announcement yesterday but lots of News
- Mortgage Innovation Product innovation continues apace. Retirement interest only mortgages were reclassified by the FCA as standard mortgages in March 2018 enabling non specialist advisers to sell them. They differ from equity release mortgages in that interest is not rolled up, there is no negative equity guarantee and they have an end date which means they are also cheaper. There was no product available on the market in 2014 and today there are 38 products available from 12 different providers. The number of mortgages available to end when people are aged over 80 has gone from 8 in 2014 to 263 in 2018. What is unusual is that all the retirement interest only product providers save one are building societies. Which underlines where innovation is coming from. Perhaps the banks are still dealing with technology and regulatory issues restriciting their ability to innovate.
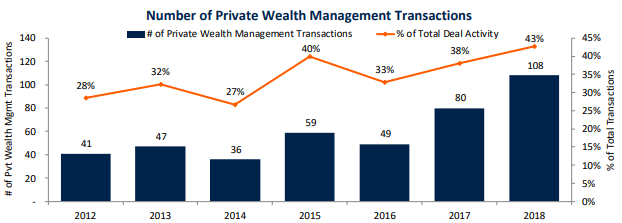
- Asset Management deals reached a record high last year with 253 deals done globally up from 210 in 2017. The previous peak was 243 in 2007. But the UK was lagging accounting for only 12% of the deals. 61% were US deals and 14% were in the ex UK Europe region. Private Wealth Management however showed the fastest growth rate.
- Schroders and Lloyds announce the name for its new financial planning arm which must have taken a long time to come up with “Schroders Personal Wealth”. It will launch in June with the transfer of £1.3bn AUM and 300 advisers from Lloyds and targets 700 advisers. It will open to “the wider market” in Q4 2019. The name seems straightforward and exhibits more awareness that the merger of the Wealth Managers Association and the Association of Professional Financial advisers. One can speculate that none of the members were sufficiently aware of the Urban Dictionary to know that PIMFA stands for “Pain In My……”.
- The FCA closed its review of the wholesale insurance broking market early yesterday concluding that there’s “nothing to see here”. However the General Insurance market study, which covers the retail market, is ongoing with The FCA’s interim report due in the summer.
- The Investment Association released a communication guide for its members yesterday. It makes good reading. Of 15 frequently used investment terms the one least understood was “Top down” and “Bottom Up” which one imagines may have a different meaning to those accustomed to the gym more than investment. It recommends using the term “Shares” in place of “Equities” and using the term “Bonds” in place of “fixed income”.
- PCF Bank – Placed 33m shares at a 20% discount to the share price to raise £10m. The placing was 52% subscribed by Somers the 65% shareholder

Rathbone – FY Results
Share Price 2250p
Mkt Cap £1.24bn
- Results PBT up 4.7% to £91.6m. Investment Management showed 3.4% pure organic growth with AUM growing to £44.1bn. Revenue was £275m. Unit trusts had £5.6bn of AUM at the year end and achieved a 34.6% operating margin to deliver £12.7m PBT. One off costs have been stripped out which is a recurring theme with Rathbone. This time there are £19.9m of acquisition costs stripped out of underlying profit which seems a large number. The dividend is raised 8.2% to 66p and the outlook is confident
- Estimates Estimates look for 22% PBT growth this year which is driven by the acquisition of Speirs & Jeffrey
- Valuation PER 16 and yield 3.1%. EV/AUM 2.5%
- Conclusion This reliable and high quality business is priced at a premium to peers and with the CFO taking over from the CEO and a ned CFO arriving on 1 April the shares may tread water until the new management team has gained a fan club

Arbuthnot Banking – Trading Statement
Share Price 1285p
Mkt Cap £191m
- Statement Underlying results are expected to be in line with expectations. There is a one off credit for the reduced earn out on the acquisition of Renaissance Asset Finance but the company stresses the customer loan balances are up 21% over the year at Renaissance. The new Commercial Asset based lending business has grown it loan book to £25m from zero in May. The professional property lending business is ready for launch.
- Estimates Estimates expect the profitability of this business to double between 2017 and 2019 which doubles the ROE from the low starting point of 2.8%
- Valuation The shares trade at a discount to the 1580p per share net asset value on account of the low ROE. PER 23, yield 3.1%
- Conclusion I like buying stocks at a discount to book value. This is just a play on the profits going up from the new lending businesses. Which looks likely to me.

TBC Bank – FY Results
Share Price 1290p
Mkt Cap £700m
- Results Net profit up 34% to GEL £130m delivering ROE of 24.3%. NIM was 6.7%, cost of risk 1.4% and cost income ratio 39.7%. Tier 1 ratio 12.8%. The new regulation in Georgia causes the company to guide to medium term loan book growth of 10-15% and a decline of 0.3% to 0.5% in NIM.
- Estimates Going forward estimates look for 16% PBT growth which with a reduced NIM and 10-15% loan book growth may be demanding unless the cost income ratio comes down.
- Valuation PER 5 X and yield 6.2%. The company trades at a 17% premium to book value for 24% ROE
- Conclusion This share is extremely cheap and growth looks set fair albeit the regulatory environment is getting harsh in Georgia. Shareholders should do well