

Chart of the Week
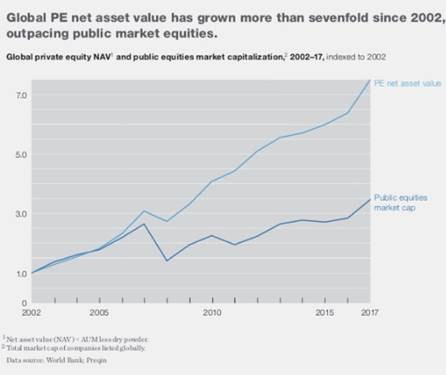
The McKinsey 2019 PE report shows that the number of US PE backed companies increased 106% over the 11 years to 2017 while the number of publicly traded companies fell 16% from 5100 to 4300. Regulation increases costs and the laws of supply and demand ensure a response. Maybe ?

.
News
- The CMA issues an enforcement order that NSF and PFG in the event of a merger must operate independently until the CMA has approved the merger. This can take some time, notwithstanding that NSF have prepared the remedy of demerging the home collected business. Another point to PFG in the battle perhaps encouraging the case for a bid for the home collected business instead.
- Jupiter CFO has resigned to take up the CFO role at RSA
- Michelle Scrimgeour, an avid book club member, has resigned from Columbia Threadneedle to take up the position of CEO of LGIM.

Morses Club – Acquisition
Share Price 159p
Mkt cap £206m
- Acquisition Morses Club has acquired Shelby Finance for £8.5m payable 50% in advance and 50% over 5 months for gross receivables of £19m. In a desperate bid to hold back analysts from raising expectations the company says it is not expected to add to earnings in the first 12 months. This is an online lender which will fit on Morses Club’s digital platform as it moves from the cash cow home collected business into the growth markets
- Estimates Look for 26% EPS growth in the year to Feb 2019 tempered to 13.7% in the year to 2020.
- Valuation ROE is c. 23% and price/book value 3.1X. PER 10.4X and yield 5.5%. By way of comparison Provident has a chance of making a positive ROE and trades at 2.3X book value. PER 11.6 and yield 5.7%. NSF has reported negative ROE also in the past and trades at 1X book value. PER 9.2 X and yield 5.9%
- Conclusion While NSF and PFG throw mud this company is emerging as the winner

Lighthouse Group PLC – FY Results
Share Price 26.5p
Mkt Cap £34m
- Results Underlying EBITDA up 7% to £3.42m and PBT up 5% to £2.64m from revenue that is modestly reduced. 67% increase in full year dividend to 0.7p. Cash up8% to £9.55m despite a £1m investment in Tavistock. Note also that balance sheet provisions have reduced from £3.9m to £0.8m over the year as legacy matters are settled. Revenue per adviser was flat at a very respectable £122k while operating costs have reduced by 3%. Auto enrolment, which is in the process of being transferred out lost £0.25m and Luceo asset management lost £0.3m. For many companies the loss from auto enrolment would be stripped out of underlying earnings. Adjusted EPS is unusually lower than reported EPS at 1.68p (2017 1.59p).
- Estimates EPS of 1.68p was modestly ahead of the 1.61p in forecasts and going forward this is expected to increase to 1.81p. The outlook refers to being in a solid position so it doesn’t look like there will be any material change.
- Valuation PER 14.7 and yield 2.6% on the dividend just reported.
- Conclusion This is an underowned company with significant strategic value by way of its affinity relationships and UK wide adviser force able to service these affinity groups. It is less acquisitive than its peers at a time when the demand for these assets is at an all time high. Earnings will continue to grow at a modest rate but let remember it was only a few years ago that there were significant provisions for legacy matters that have now been paid off and cash generation is now accelerating while AUM is starting to build in house through Luceo. 35p may be a reasonable expectation for shareholders