
Bushveld Minerals* (BMN LN) – Vanchem acquisition adds significant value
MiFID II exempt information – see disclaimer below
Bushveld Minerals* (BMN LN) 26.5p, Mkt Cap £294m – Vanchem acquisition unlocks Mokopane Project adding 5,000mtVpa of vanadium production capacity
BUY – Target price 90p from 87p
- Vanchem acquisition for $68m cash adds real value due to its combination with Bushveld’s nearby Mokopane project which can supply much-needed fresh ore to Vanchem.
- Vanchem technically has capacity of 5,000mtVpa but currently produces just ~960mtVpa.
- Capex est. $45m to restore capacity plus $20m for new Mokopane mine construction.
- Our new Mokopane/Vanchem NPV looks good at US$461m, IRR strong at 63% due to low capital outlay and faster production growth on 10% discount rate.
- Vanchem currently in business administration due to lack of own resources and feedstock from closure of Highveld steel in 2016.
- Production running off just one of three kilns at Vanchem.
- Low-risk expansion using existing kilns, and equipment, simply replaces lost production.
- Vanchem’s vanadium chemicals business helps diversify sales while the increase in production still leave scope for further expansion at Vametco.
- Valuation: We have reduced our assumed vanadium price to $60/kgVfor 2019 and 2020 due to lesser compliance with the new Chinese regulations than expected, though we do expect punishment of Chinese officials to create better compliance this year. Vanchem acquisition offsets our assumed lower vanadium prices.
- Our revised target price valuation rises to 90p/s from 87p/s previously.
- Energy Tech: Bushveld Energy initial valuation as sales of Vanadium Redox Flow Batteries ‘VFRBs’ to ESKOM and others draw closer. Higher vanadium production give potential to significantly expand VFRB electrolyte sales. We value Bushveld Energy at 3.6/s as an initial starter valuation though the business should develop significantly greater value in time.
|
Vametco & Vanchem |
|
2018 |
2019 |
2020 |
2021 |
2022 |
2023 | |
|
Price V2O5 |
$/lb |
|
19.2 |
14.0 |
14.0 |
12.8 |
10.3 |
10.3 |
|
Ferro Vanadium |
US$/kg |
|
81.2 |
60.0 |
60.0 |
55.0 |
45.0 |
45.0 |
|
Vanadium sales |
kg |
|
2573 |
3096 |
4370 |
5432 |
6422 |
7911 |
|
Sales |
US$m |
|
178.0 |
171.6 |
242.3 |
276.1 |
267.0 |
328.9 |
|
Operating costs |
US$m |
|
70.5 |
74.9 |
94.5 |
113.5 |
127.3 |
152.6 |
|
Operating costs |
US$/kg |
|
27.4 |
24.2 |
21.6 |
20.9 |
19.8 |
19.3 |
|
Operating profit |
US$m |
|
107.5 |
97.1 |
149.2 |
164.8 |
142.1 |
180.2 |
|
Pre-tax profit |
US$m |
|
106.8 |
91.9 |
142.3 |
157.4 |
134.5 |
172.8 |
|
tax |
US$m |
|
30.4 |
26.2 |
40.5 |
44.9 |
38.3 |
49.2 |
|
Post-tax profit |
US$m |
|
76.3 |
65.7 |
101.7 |
112.6 |
96.2 |
123.5 |
|
EPS |
US$c/s |
|
6.9 |
5.9 |
9.2 |
10.1 |
8.7 |
11.1 |
|
PE |
x |
|
5.0 |
5.8 |
3.8 |
3.4 |
4.0 |
3.1 |
|
EV/EBITDA |
x |
|
3.9 |
4.3 |
2.8 |
2.6 |
3.0 |
2.3 |
|
EBITDA |
US$m |
|
107.5 |
97.1 |
149.2 |
164.8 |
142.1 |
180.2 |
|
Free Cash Flow |
US$m |
|
74.0 |
5.5 |
87.1 |
120.7 |
103.7 |
148.3 |
|
Vametco Cash Flow |
US$m |
74% |
74.0 |
59.9 |
78.8 |
84.0 |
68.0 |
71.6 |
|
Vanchem Cash Flow |
US$m |
100% |
|
-54.5 |
8.3 |
36.7 |
35.6 |
76.7 |
- Bushveld management have been looking over the fence at Vanchem in South Africa as combining the assets appears to be the best and most cost-effective way of developing their Mokopane vanadium project.
- The deal to acquire Vanchem out of Business Administration for $68m in cash is subject to regulatory approvals and gives Bushveld immediate access to an additional 960tpa of vanadium production capacity plus infrastructure to expand to 4,200tpa.
- Payment: US$6.8m is to be paid in cash on 30 April 2019 plus US$61.2m settled no sooner than 31 July 2019 and no later than 31 October 2019.
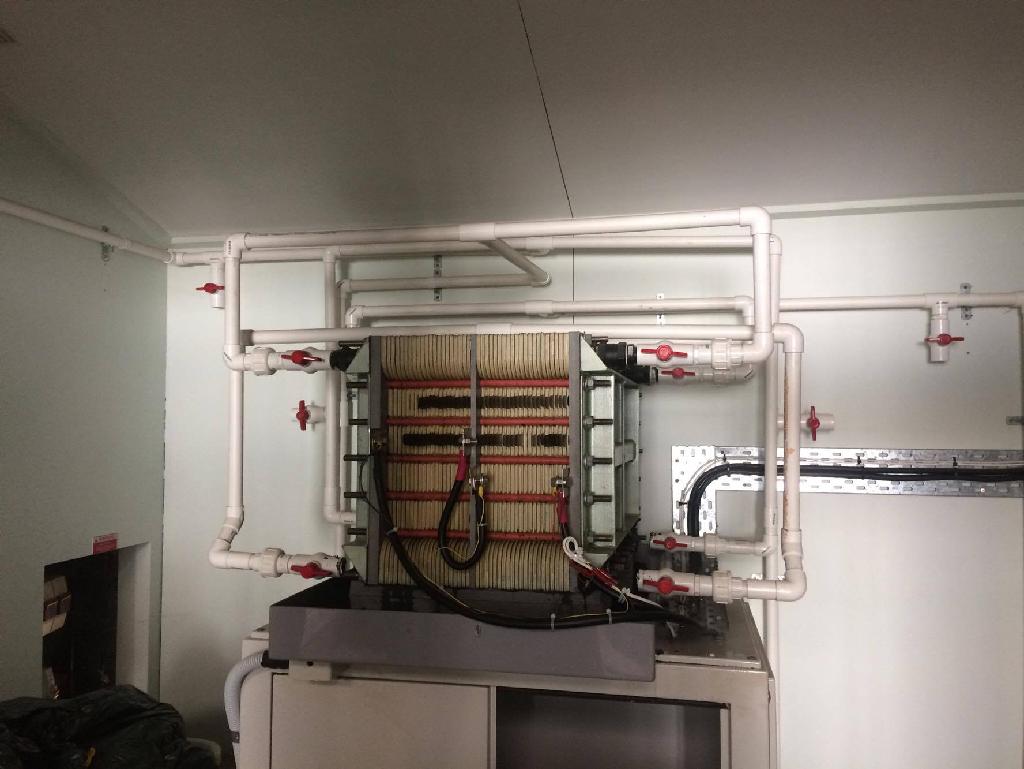
- Vanchem is currently operating one out of three furnaces with production currently reduced to just 960mtVpa due to a lack of suitable feedstock and constrained resources, though this should more than double in 2021 as the Mokopane mine comes on stream.
- Capital expenditure of $45m is planned to restore the plant to 5,000mtVpa of capacity in the form of various vanadium chemical products.
- Mokopane: Developing the new open cast mine and infrastructure at Mokopane will cost just $20m which added to the $68m acquisition cost and $45m of capital is just $133m vs the previously estimated development cost at Mokopane of $298m.
- Mokopane ore is a very high 70% magnetite which serves to offset transport and logistics costs when compared with Vametco.
- The acquisition adds immediately to Bushveld vanadium production without adding any new vanadium to the market enabling management to take advantages of current vanadium prices.
- Vanchem is a cheap deal for Bushveld as the business was starved of feedstock and was forced into business rescue by the closure of Highveld which formerly supplied slag and Mapochs mine feedstock to the Vanchem plant. We note some modification will be done to adjust to feedstock from Mokopane.
- Comparing the Vanchem acquisition with the original Mokopane PFS shows the Vanchem deal to work better on virtually every metric and critically the deal serves to simply take over and replace Vanchem production which was lost to the market last year.
- Our new Mokopane/Vanchem NPV is better at US$487m vs US$418m in the 2016 Mokopane PFS assuming a 10% discount rate and our IRR is at 66% vs 24% in the 2016 PFS.
- Chemicals: Vanchem is a large chemicals business focussed on vanadium chemicals and products. It has multiple product streams and lots of big kit for spare capacity. It is also well connected to Vametco and Mokopane by rail and road which gives increased flexibility in its operations and potential for create for more value-added products.
- Cheaper acquisition: Vanchem is a significantly cheaper acquisition on a per tonne of capacity basis than the Vametco deal due to its distressed state, need for feedstock and capex requirements.
- The capital intensity of the Vanchem deal is around $17,000/t of V2O5 on our figures vs around $31,000/t in the Mokopane 2016 PFS.
- Production is currently running off just one of three existing kilns at Vanchem and the new $45m capital program to restore production over the next five years is seen by management as relatively cautious.
- The plan allows for existing production to continue while refurbishing capacity which was recently mothballed for lack of feed. Hopefully reality will be faster given the presence of so much infrastructure at site.
- Replacing lost capacity: The strategy simply replaces vanadium production which was lost to the market after Highveld closed and should have little impact on vanadium prices.
- Highveld Steel closed in 2016 left for dead by Evraz, its Russian owner which cut around 1,800 jobs in the process. We have seen reports suggesting the plant may reopen sometime though this may require higher steel prices, a weaker South African rand or both.
- Vanadium deficit: Vanadium remains in structural deficit in the market according to Bushveld supported by 2.5% compound demand growth from steel and chemicals and potential for CAGR growth of up to 8.4% driven by vanadium redox batteries.
- Vanadium prices have fallen this year due to China’s failure to fully implement its new standards on vanadium content in steel rebar. The result is that many smaller steel mills are still making brittle steel by quenching and tempering which is not good if corroded or unexpected strain is put on its reinforced structure.
- Chinese officials are being punished for failure to implement government policies and we expect more officials to move to impose standards rather than risk several years in a correctional facility.
- We have adjusted our model to replace our forecast $150m expansion at Vametco with new and less capital-intensive production from Vanchem.
- While we suspect management will be busy restoring production at Vanchem it is possible that Vametco could also expand further in time if the supply deficit widens and prices continue to support additional supply.
- This is good news for consumers as it offers the prospect for an additional vanadium supply into a market which could potentially see longer term constraint as banks may struggle to finance many other vanadium projects.
- Assumptions: We have reduced our ferro-vanadium price assumption to $60/kgV from US$75/kgV for 2019 and 2020 based on the assumption that ferro-vanadium prices average current price levels through the rest of the year.
- Our price assumptions of US$55/kgV for 2021 and US$45/kgV for 2022 onwards remain the same.
- We suspect ferro-vanadium prices may dip further before recovery later in the year as Chinese officials better implement government regulations introduced last year.
- Production: We have combined our production assumptions for the Vametco and Vanchem plants. Our new production figures reflect our best guess for the combined output of the two plants. We see an acceleration in the increase in vanadium production but are more cautious as we assume production is around 80% of capacity going forward.
- Bushveld Energy: We have modelled some basic assumptions for Bushveld Energy for incorporation into our valuation. We assume relatively modest margins for the business on project management of Vanadium Flow Redox Batteries ‘VFRBs’ into the South African grid. We also assume a more modest margin on the production of electrolyte based on the value of the vanadium pentoxide contained.
Conclusion: The combination of Mokopane with Vanchem is a great way forward for Bushveld Minerals. The deal given immediate access to production and near-term expansion at relatively low capital cost and technical risk.
It broadens the range of value-added vanadium products and enables greater operational flexibility with vanadium pentoxide to feed Bushveld Energy’s planned electrolyte plant.
This should give the team greater confidence to take on contracts for vanadium electrolyte for the next generation of VFRB batteries to be built in South Africa for energy storage and grid balancing.
A worrying number of fires in Li-ion storage facilities suggests that VFRB may not only be a more economic way forward but may also be the only relatively fire-safe way forward for Megawatt-scale grid storage.
We retain our Strong Buy recommendation
Our valuation rises to 90 pence per share from 87p/s previously
Analysts
John Meyer – 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
James Mills -0203 470 0496
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
Abigail Wayne – 0203 470 0534
Rob Rees – 0203 470 0535
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
DISCLAIMER
This note is a marketing communication and comprises non-independent research. This means it has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination.
This note is intended only for distribution to Professional Clients and Eligible Counterparties as defined under the rules of the Financial Conduct Authority and is not directed at Retail Clients.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
This note has been issued by SP Angel Corporate Finance LLP (‘SPA’) to promote its investment services. Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. The information contained herein is based on sources which we believe to be reliable, but we do not represent that it is wholly accurate or complete. All opinions and estimates included in this report are subject to change without notice. It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. SPA is not responsible for any errors or omissions or for the results obtained from the use of such information. Where the subject of the research is a client company of SPA we may have shown a draft of the research (or parts of it) to the company prior to publication to check factual accuracy, soundness of assumptions etc.
Distribution of this note does not imply distribution of future notes covering the same issuers, companies or subject matter.
Where the investment is traded on AIM it should be noted that liquidity may be lower and price movements more volatile.
SPA, its partners, officers and/or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SPA is registered in England and Wales with company number OC317049. The registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SPA is authorised and regulated by the UK Financial Conduct Authority and is a Member of the London Stock Exchange plc.
MiFID II - Based on our analysis we have concluded that this note may be received free of charge by any person subject to the new MiFID II rules on research unbundling pursuant to the exemptions within Article 12(3) of the MiFID II Delegated Directive and FCA COBS Rule 2.3A.19.
A full analysis is available on our website here http://www.spangel.co.uk/legal-and-regulatory-notices.html. If you have any queries, feel free to contact our Compliance Officer, Tim Jenkins (tim.jenkins@spangel.co.uk).
SPA research ratings – Based on a time horizon of 12 months: Buy = Expected return of more than 15%, Hold = Expected return between -15% and +15%, Sell = Expected return of less than 15%
Click this link to unsubscribe
|
Vametco & Vanchem |
|
2017 |
2018 |
2019 |
2020 |
2021 |
2022 |
2023 | |
|
Price V2O5 |
$/lb |
|
6.4 |
19.2 |
14.0 |
14.0 |
12.8 |
10.3 |
10.3 |
|
Ferro Vanadium |
US$/kg |
|
32.6 |
81.2 |
60.0 |
60.0 |
55.0 |
45.0 |
45.0 |
|
Vanadium sales |
kg |
|
2586 |
2573 |
3096 |
4370 |
5432 |
6422 |
7911 |
|
Sales |
US$m |
|
71.8 |
178.0 |
171.6 |
242.3 |
276.1 |
267.0 |
328.9 |
|
Operating costs |
US$m |
|
57.7 |
70.5 |
74.9 |
94.5 |
113.5 |
127.3 |
152.6 |
|
Operating costs |
US$/kg |
|
22.3 |
27.4 |
24.2 |
21.6 |
20.9 |
19.8 |
19.3 |
|
Operating profit |
US$m |
|
14.2 |
107.5 |
97.1 |
149.2 |
164.8 |
142.1 |
180.2 |
|
Pre-tax profit |
US$m |
|
13.9 |
106.8 |
91.9 |
142.3 |
157.4 |
134.5 |
172.8 |
|
tax |
US$m |
|
4.0 |
30.4 |
26.2 |
40.5 |
44.9 |
38.3 |
49.2 |
|
Post-tax profit |
US$m |
|
9.9 |
76.3 |
65.7 |
101.7 |
112.6 |
96.2 |
123.5 |
|
EPS |
US$c/s |
|
0.9 |
6.9 |
5.9 |
9.2 |
10.1 |
8.7 |
11.1 |
|
PE |
x |
|
38.5 |
5.0 |
5.8 |
3.8 |
3.4 |
4.0 |
3.1 |
|
EV/EBITDA |
x |
|
29.8 |
3.9 |
4.3 |
2.8 |
2.6 |
3.0 |
2.3 |
|
EBITDA |
US$m |
- |
14.2 |
107.5 |
97.1 |
149.2 |
164.8 |
142.1 |
180.2 |
|
Free Cash Flow |
US$m |
- |
11.8 |
74.0 |
5.5 |
87.1 |
120.7 |
103.7 |
148.3 |
|
Vametco Cash Flow |
US$m |
74.00% |
11.8 |
74.0 |
59.9 |
78.8 |
84.0 |
68.0 |
71.6 |