
Although when discussing any outsourcer these days it is difficult to banish the memory of Carillion and the general car crash in this particular area of the stock market, just in case there is to be a turn around, it appears brave / worthwhile going where angels fear to tread. In addition, given the aftermath of the late Carillion, the powers that be amongst its former counterparts not only have lessons to learn, but have the opportunity of making themselves more robust than before. The primary aspect for management to look at is of course to reduce debt, and to this end the market may expect an imminent announcement in this respect, Given the way the way that there was a spike in buying volume in the last week of February for shares of Capita, a discreet distance between rumour and likely annoucement alongside this week's earnings release on Thursday March 14.
Clearly, despite hopes of a decent disposal for the £2bn there are risks to would be bulls. For instance, cutting the dividend yield from 3% is a way of cutting costs, and while there is the probability of better news on trading, we may still be holding our breath until the news is finally out. The stock is currently trading back at its 50 day moving average around 116p, but it may be that the shares are only finally out of the woods on a break of recent highs / 200 day moving average at 131p. Nevertheless, given the way that there has already been a decline from 600p plus a few years ago, only fresh horror would take Capita to new lows.
Although when discussing any outsourcer these days it is difficult to banish the memory of Carillion and the general car crash in this particular area of the stock market, just in case there is to be a turn around, it appears brave / worthwhile going where angels fear to tread. In addition, given the aftermath of the late Carillion, the powers that be amongst its former counterparts not only have lessons to learn, but have the opportunity of making themselves more robust than before. The primary aspect for management to look at is of course to reduce debt, and to this end the market may expect an imminent announcement in this respect, Given the way the way that there was a spike in buying volume in the last week of February for shares of Capita, a discreet distance between rumour and likely annoucement alongside this week's earnings release on Thursday March 14.
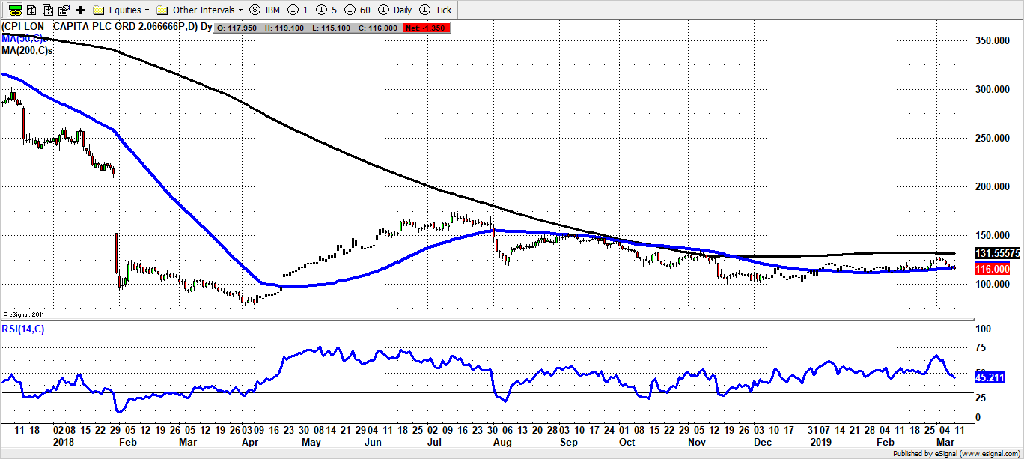
Clearly, despite hopes of a decent disposal for the £2bn there are risks to would be bulls. For instance, cutting the dividend yield from 3% is a way of cutting costs, and while there is the probability of better news on trading, we may still be holding our breath until the news is finally out. The stock is currently trading back at its 50 day moving average around 116p, but it may be that the shares are only finally out of the woods on a break of recent highs / 200 day moving average at 131p. Nevertheless, given the way that there has already been a decline from 600p plus a few years ago, only fresh horror would take Capita to new lows.